


Benchmark Dutch TTF natural gas prices climbed above 97 euros per megawatt-hour on Monday, the first time at that level since the 2022 energy crisis, according to Bloomberg. The move came as meteorologists forecast temperatures across parts of continental Europe to fall 2 C to 3 C below normal starting this weekend, the report stated.
The cold snap is expected to hit northeastern China, Japan and South Korea as well, with temperatures well below seasonal averages, according to the forecast. The simultaneous demand pull from major energy-consuming regions has focused attention on Europe's unusually low stockpiles just as the withdrawal season begins.
Traders cited the combination of early cold and limited storage as the primary driver of the price surge. The benchmark has been rising steadily in recent sessions, and the 100-euro mark is now within reach for the first time in nearly four years, market data showed.
Storage Levels Below Seasonal Average as Withdrawal Period Begins
European storage facilities are 75% full, compared with a 10-year average of around 90% for this time of year, according to the report. Gas Infrastructure Europe data showed last Thursday that EU natural gas inventories declined for the first time this year, marking the start of the winter drawdown.
The seasonally low inventories leave limited buffers to shield the continent from back-to-back cold blasts, the report stated. Analysts noted that storage levels typically peak in late October or early November, making the current deficit particularly concerning as heating demand begins to rise.
Historical precedent underscores the risk. During the 2009 Russia-Ukraine gas conflict, western European storage was filled to 73 percent of working gas volumes, a level that provided a cushion against supply disruptions, according to a 2011 study by Stefan Lochner in Energy Policy [1]. Current levels are only slightly higher, but the supply landscape has changed markedly since then.
U.S. and European Natural Gas Markets Diverge on Weather Forecasts
US natural gas futures have fallen to levels last seen in April as unusually warm weather across the Lower 48 suppresses heating demand, according to the report. The Commodity Weather Group expects US October and November combined to be the third-warmest such period since records began in 1950, reinforcing expectations for a mild winter driven by El Niño.
The divergence highlights the widening split between the two energy markets, Bloomberg reported. While Europe braces for early cold, the United States is experiencing above-normal temperatures that have curtailed gas consumption for heating and power generation.
Market participants are watching the contrast closely. The US benchmark, Henry Hub, has been pressured by abundant supply and weak demand, whereas Europe's TTF has been driven higher by supply concerns and competition for LNG cargoes. The split reflects differing weather patterns and storage positions on each side of the Atlantic.
Smaller Buffer Leaves Europe Dependent on International Market
Europe must compete with Asian buyers in the international market, which suggests TTF prices will have to rise sharply as the Hormuz maritime chokepoint remains chaotic, according to the report. The Strait of Hormuz is a critical transit route for LNG, and any disruption there tightens global supply.
Andrew Pedrini, a meteorologist at Atmospheric G2, said what markets likely fear most heading into winter is 'joint cold across multiple high-energy-demand regions.' That scenario would pit Europe against Asia for scarce LNG cargoes, driving prices higher.
The report stated that the region's limited storage buffer increases its exposure to global supply disruptions. With inventories below seasonal norms, Europe has less flexibility to absorb shocks, making it more reliant on timely and affordable imports.
Outlook for Winter Energy Prices
The cold snap forecast and low storage levels indicate Europe faces an early winter stress test, according to Bloomberg. The combination of below-normal temperatures and above-average storage deficits has created a precarious balance between supply and demand.
Market participants are watching weather patterns and international supply routes, the report stated. Any escalation in the Strait of Hormuz or unexpected cold spells could further strain Europe's energy system.
No official forecasts for specific price levels were provided, but the report noted that TTF prices have already climbed above 97 euros per megawatt-hour. The 100-euro threshold remains a key psychological marker for traders and policymakers alike.
Reference
- Modeling the European natural gas market during the 2009 Russian-Ukrainian gas con?ict: Ex-post simulation and analysis. Stefan Lochner. Energy Policy 2011
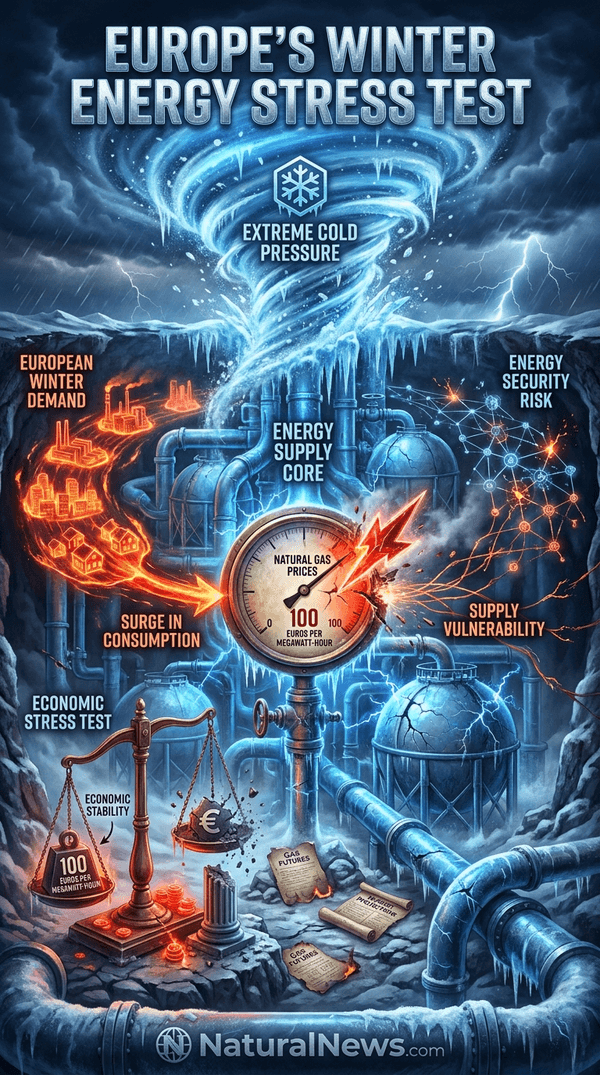
Explainer Infographic
Please contact us for more information.